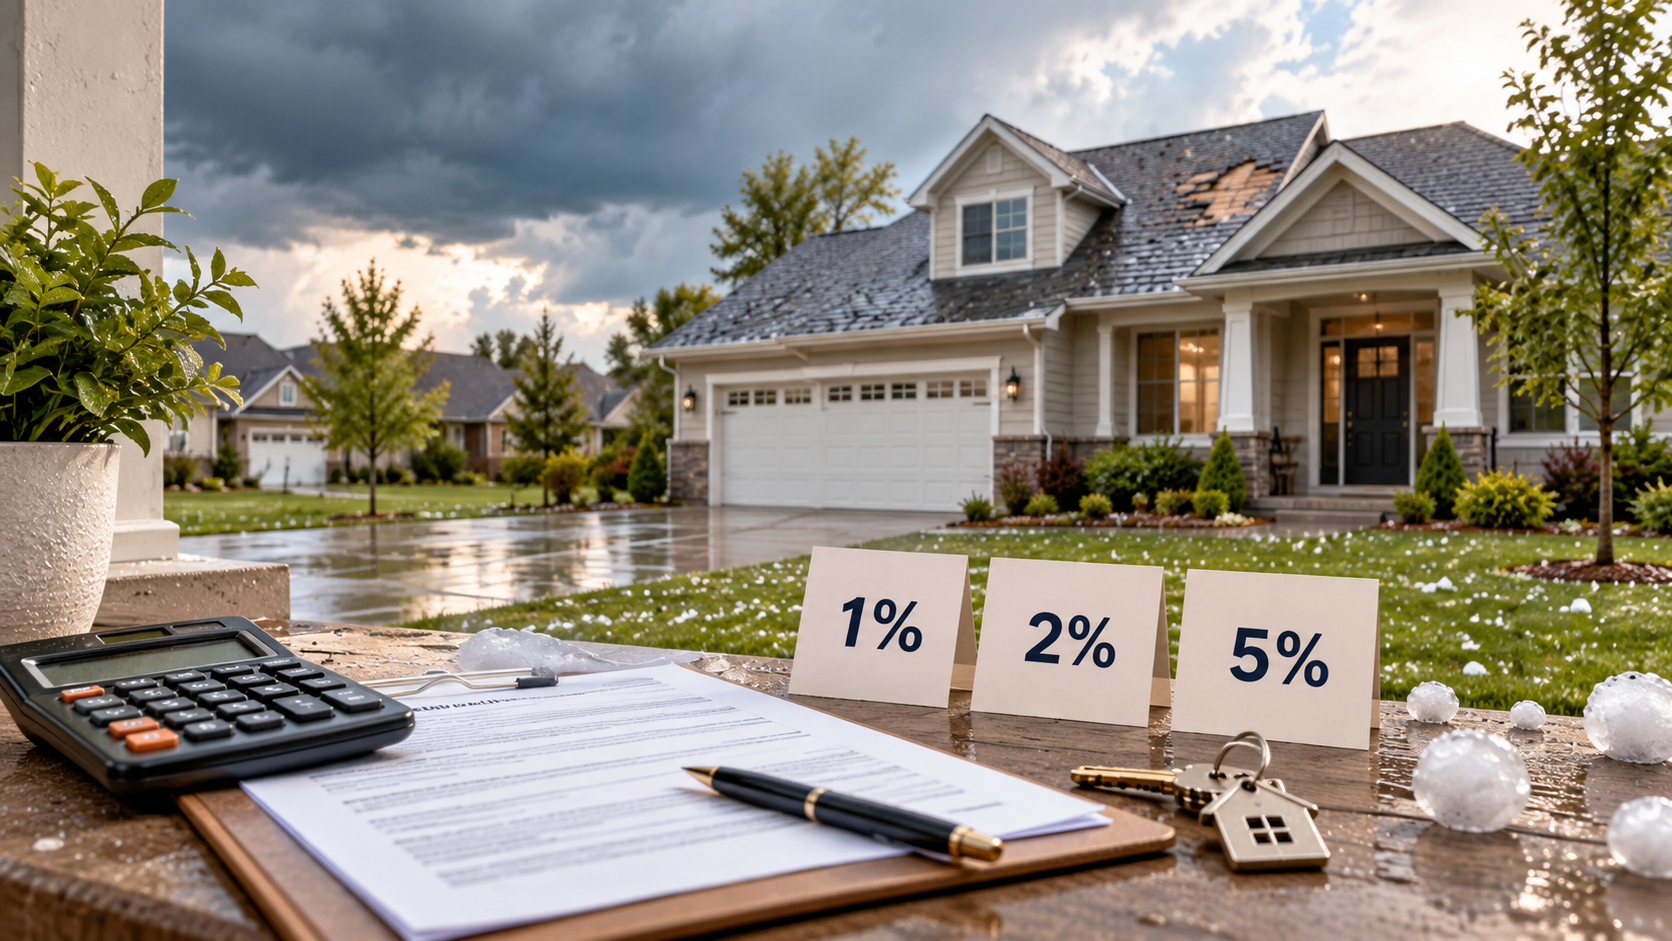
A home insurance quote can look reassuring until you read the deductible. A buyer may see a manageable annual premium and assume that a storm-damaged roof will be a relatively small expense. Then a hailstorm arrives, and the policyholder learns that the wind-and-hail deductible is 2% of the home’s insured dwelling limit—not $2,000.
On a home insured for $400,000, that 2% deductible is $8,000. A 5% deductible is $20,000. Those are not estimates of the cost of a storm; they are amounts the homeowner may have to absorb before an insurer pays a covered claim.
This distinction matters in 2026. In its March 18, 2026 report, insurance marketplace Insurify estimated that the average annual U.S. home insurance premium rose 12% in 2025 and projected a further 4% increase by the end of 2026. That is a private-market projection, not a guaranteed rate increase for any particular property. The same report described homeowners accepting higher deductibles and changes to roof coverage as insurers respond to weather-related losses.
For buyers, the practical question is no longer just, “Can I afford the insurance premium?”
It is also, “Could I afford to use this policy after a serious storm?”
Why Home Insurance Deductibles Matter More in 2026
Premiums and deductibles are different parts of the same financial decision. The premium is what you pay to keep coverage in force. The deductible is the portion of a covered loss you bear when you make a claim.
A policy with a higher deductible may have a lower premium. But the savings can disappear quickly if a major loss occurs. That trade-off is especially important in places where hail, wind or hurricanes are realistic concerns.
Homebuyers should therefore evaluate insurance in two ways: the recurring annual expense and the amount of cash they might need after a covered disaster.
What Is a Homeowners Insurance Deductible?
A homeowners insurance deductible is the part of a covered claim the policyholder is responsible for before the insurer pays its share, subject to the policy’s limits, exclusions and settlement terms.
For example, imagine an otherwise covered $12,000 repair claim with a $2,000 deductible. If the insurer agrees the covered loss is $12,000 and no other limitations apply, the insurer’s payment would generally be $10,000. The homeowner bears $2,000.
Flat-Dollar vs. Percentage Deductibles
A flat-dollar deductible is stated as an amount such as $1,000 or $2,500. A percentage deductible is calculated from a specified policy limit, commonly the dwelling coverage limit (often called Coverage A).
That percentage is generally not calculated from the home’s sale price, the outstanding mortgage balance or the repair invoice. Read the actual policy to identify the base used.
How Much Is a 1%, 2% or 5% Deductible?
Use this formula:
Percentage deductible in dollars = dwelling coverage limit × deductible percentage.
| Insured Dwelling Limit | 1% Deductible | 2% Deductible | 5% Deductible |
|---|---|---|---|
| $250,000 | $2,500 | $5,000 | $12,500 |
| $400,000 | $4,000 | $8,000 | $20,000 |
| $600,000 | $6,000 | $12,000 | $30,000 |
| $800,000 | $8,000 | $16,000 | $40,000 |
These are arithmetic examples, not statements that a given insurer offers all three options.
Now consider a $400,000 dwelling limit and a covered hail claim with $14,000 in approved repairs. With a 1% deductible, the homeowner’s share would generally be $4,000 and the insurer’s share $10,000. With a 2% deductible, the homeowner’s share would be $8,000 and the insurer’s share $6,000. With a 5% deductible, the approved repair amount is below the $20,000 deductible, so the insurer would generally pay nothing on that claim.
| $14,000 Covered Hail Claim ($400,000 Dwelling Limit) | Homeowner Pays | Insurer Pays |
|---|---|---|
| 1% deductible ($4,000) | $4,000 | $10,000 |
| 2% deductible ($8,000) | $8,000 | $6,000 |
| 5% deductible ($20,000) | $14,000 | Generally nothing |
Wind, Hail, Hurricane and Named-Storm Deductibles Are Not Identical
A standard deductible might apply to a kitchen fire while a separate wind-and-hail deductible applies to a damaged roof. In another policy, a special deductible might apply only when a hurricane or named storm meets the policy’s trigger conditions.
According to the National Association of Insurance Commissioners (NAIC), as of June 2025, 19 states and Washington, D.C., had some form of hurricane or named-storm deductible in place. The NAIC also notes that percentage-based hurricane deductibles can vary substantially. State rules and available policy options differ, so there is no universal national deductible.
Texas and Hail-Prone Markets
For buyers in Dallas–Fort Worth, Houston, Austin and other Texas communities, wind and hail terms deserve particular attention. Hail can affect roofs far from the coast, while coastal homes may face additional windstorm arrangements.
The Texas Department of Insurance advised homeowners in March 2026 to check whether the wind-and-hail deductible is higher than the deductible for other losses. It also recommended verifying roof age, materials and whether the policy pays replacement cost or a depreciated amount.
Florida and Hurricane Deductibles
Florida’s hurricane deductible rules are more specific than a generic per-claim example. The Florida Department of Financial Services explains that insurers must offer certain hurricane deductible choices, with exceptions based on dwelling limits, and that hurricane deductibles are generally applied on a calendar-year basis under Florida law.
A Florida buyer should ask the agent to identify the exact dollar amount shown on the declarations page and explain when the hurricane deductible is triggered. The buyer should also ask how subsequent hurricane losses in the same calendar year would be handled.
What Happens When You File a Claim?
A deductible is typically subtracted from the insurer’s calculation of a covered claim; it is not necessarily a separate bill that you first send to the insurance company. You still need funds to pay the deductible portion of repairs.
The Texas Department of Insurance explains that home and auto deductibles commonly apply to each claim, unlike an annual health insurance deductible. However, special catastrophe rules can differ; Florida’s hurricane deductible is an important example.
Before filing a claim, document the damage, take steps to prevent further covered damage when safe, and contact your insurer. Ask how the damage will be assessed and which deductible applies. Avoid assuming that a contractor’s repair estimate is the same as the insurer’s approved covered loss.
Roof Replacement Cost vs. Actual Cash Value
The deductible is only half the roof-insurance question. The other half is how the insurer values the roof.
With replacement-cost coverage, a covered roof loss may be settled using the cost to repair or replace with comparable materials, subject to policy terms and often a process for recovering withheld depreciation after repairs are completed.
With actual-cash-value coverage, depreciation is deducted from the replacement amount. An older roof may therefore produce a much smaller payment than a new roof would, even before the deductible is applied.
For a simplified illustration, imagine approved roof replacement costs of $18,000. If the insurer values the roof at $11,000 after depreciation and a $5,000 deductible applies, an actual-cash-value settlement might produce only $6,000. The homeowner could face the rest of the replacement bill. A replacement-cost policy might ultimately pay more if its conditions are met.
| Actual-Cash-Value Roof Example | Amount |
|---|---|
| Approved roof replacement cost | $18,000 |
| Roof value after depreciation | $11,000 |
| Deductible | $5,000 |
| Possible actual-cash-value settlement | $6,000 |
The Texas Department of Insurance warned in April 2026 that some policies switch aging roofs to actual-cash-value treatment or limit roof coverage. Ask specifically about cosmetic-damage exclusions, roof-surface payment schedules, matching limitations and any separate roof deductible.
How to Compare Two Home Insurance Quotes
Suppose Quote A costs $2,700 annually and has a 1% wind-and-hail deductible. Quote B costs $2,350 and has a 2% deductible. On $400,000 of dwelling coverage, Quote B saves $350 in premium per year but increases the potential deductible from $4,000 to $8,000.
| $400,000 Dwelling Coverage | Quote A | Quote B |
|---|---|---|
| Annual premium | $2,700 | $2,350 |
| Wind-and-hail deductible | 1% ($4,000) | 2% ($8,000) |
That is a $4,000 difference in out-of-pocket exposure in exchange for $350 in annual premium savings.
Compare quotes using the same dwelling limit, coverage form, roof settlement method, liability limits and optional endorsements. Then review the standard deductible and each special deductible separately.
The Consumer Financial Protection Bureau (CFPB) recommends obtaining written quotes from several insurers and comparing coverage and cost. It also suggests asking how changing the deductible affects the premium. A lower quote may reflect less protection rather than a better bargain.
What Buyers Should Check Before Closing
Do not wait until the final week of escrow to investigate insurance. Most mortgage lenders require homeowners coverage, and the CFPB recommends sharing proposed policies with your loan officer to confirm that they meet lender requirements.
Request the full quote and, when available, the policy declarations and relevant endorsements. Ask the agent to answer these questions in writing:
- What is the dwelling coverage limit used to calculate percentage deductibles?
- What is the deductible for fire, theft and other standard covered losses?
- Is there a separate wind, hail, hurricane, named-storm or roof deductible?
- What is each percentage deductible in dollars today?
- Which weather events trigger each deductible?
- Does the roof receive replacement-cost or actual-cash-value coverage?
- Are flood, windstorm or other risks excluded or insured separately?
- Could the roof’s age or condition change eligibility or coverage after inspection?
- Does the proposed coverage meet the lender’s requirements?
- What would the premium be with a lower deductible, if offered?
How to Prepare for a Large Deductible
A high deductible is easier to manage when it is planned rather than discovered after a storm. Calculate the largest applicable dollar deductible on your policy and compare it with your accessible emergency savings.
If your wind-and-hail deductible is $10,000, ask whether you could realistically pay that amount while continuing mortgage payments, utilities and other obligations. A separate reserve for home repairs can help, particularly when a roof, HVAC system or plumbing repair is already foreseeable.
Frequently Asked Questions
Is a 2% homeowners insurance deductible $2,000?
Not unless the applicable insured value is $100,000. A 2% deductible on a $400,000 dwelling limit is $8,000. Check which coverage limit your policy uses.
Does a wind-and-hail deductible apply to every claim?
No. It generally applies to losses that meet the policy’s wind-and-hail terms. Other covered losses may have a different deductible. Read the endorsements and ask your insurer about the event trigger.
Is the deductible based on the home purchase price?
Usually not. Percentage deductibles are commonly based on the insured dwelling limit, which may differ from the sale price and mortgage balance. The policy controls the calculation.
Do I pay a homeowners insurance deductible every year?
Not simply because another year begins. A deductible generally matters when you have a covered claim. Some catastrophe deductibles have special annual application rules, such as Florida’s hurricane deductible.
Does homeowners insurance cover flood damage after a hurricane?
Standard homeowners insurance generally excludes flooding, even when the flood occurs during a hurricane. Flood insurance is usually separate. Wind damage and flood damage can have different coverage and claim rules.
The Bottom Line
When comparing homes in 2026, add one more number to your affordability calculation: the largest deductible you might have to pay after a covered storm.
A 2% or 5% deductible can mean thousands or tens of thousands of dollars. Roof depreciation, separate peril deductibles and exclusions can increase the amount you ultimately pay. None of those details is captured by the annual premium alone.
Before closing or renewing, get written quotes, convert every percentage into dollars, check roof settlement terms and confirm coverage with your lender.
A policy should be affordable to maintain—and financially workable when you need to use it.
Related Reading
- Buying a Home in a High-Risk Area in 2026: How to Check Climate Risk, Insurance Costs and Flood Exposure Before You Buy
- Buying an Older Home in 2026: Check These Insurance, Roof and Inspection Issues Before You Close
- Home Price Cuts Are Surging in 2026: What Buyers Should Negotiate Beyond the Asking Price
Sources
- Insurify — 2026 Insuring the American Homeowner Report (March 18, 2026). Proprietary data and projection, not an official government premium index.
- NAIC — Hurricane Deductibles
- NAIC — Homeowners Insurance overview
- Texas Department of Insurance — What to know about insurance and your roof (March 2026)
- Texas Department of Insurance — Insurance and your roof (April 1, 2026)
- Texas Department of Insurance — What to know about deductibles
- Florida Department of Financial Services — Florida’s Hurricane Deductible
- CFPB — Shop for homeowner’s insurance
- CFPB — Loan Estimate explainer
Editorial note: Calculations are hypothetical examples. Policy language and state rules control actual coverage and payments.